

UKG Wallet analysis by Appwee
Getting access to money I had already earned is a very different experience from waiting for the normal payday, and that is the central reason UKG Wallet caught my attention. This free business app from UKG, Inc. is built around earned-wage access, so its usefulness depends less on entertainment or daily content and more on whether it fits the way your employer handles payroll. In my experience, that makes it immediately appealing during a tight week, but also more conditional than an ordinary budgeting or banking app.
The first thing I would tell a friend is simple: UKG Wallet is not a replacement for a bank account, a full budgeting tool, or an employer payroll system. It is a focused companion for accessing earned wages through a participating workplace. That distinction matters. If your employer supports the service and you occasionally need earlier access to pay you have already earned, it can become a practical part of your routine. If you are looking for investment tools, detailed spending analysis, or a general-purpose money manager, you will probably find a different category of app more suitable.
How UKG Wallet feels during the first week
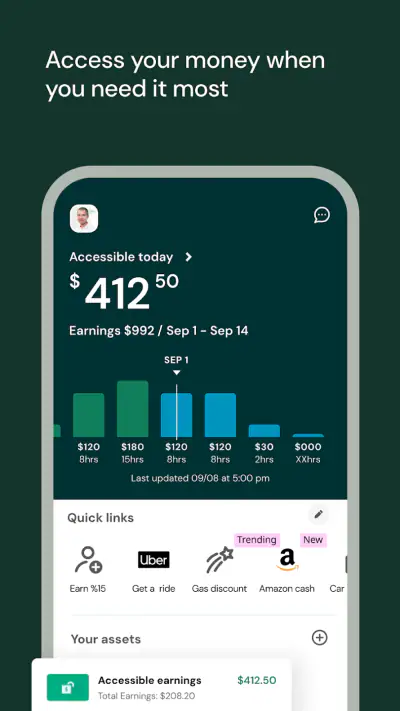
The first-week appeal comes from the directness of the idea. Instead of treating income as something that appears only on the scheduled payday, the app is designed to help you reach earned wages when you need them. That can be especially useful after an unexpected expense, during a week with unusually high travel costs, or when a bill arrives just before payday. The benefit is not abstract: it is about reducing the gap between doing the work and having access to the resulting pay.
That convenience also sets the right expectation for setup. The app cannot create access on its own. Your employer’s relationship with UKG and the way your wages are recorded are central to the experience. I would check workplace eligibility before building a financial routine around it. A polished app cannot overcome an employer that does not support the relevant service or a payroll workflow that does not provide the information needed for access.
UKG Wallet has a store rating of 4.5 from around twelve thousand ratings, which suggests that many people find the basic purpose worthwhile. It has passed the novelty stage for a meaningful audience, but ratings should still be read in context. A positive experience here is likely to depend on whether the app works smoothly with a person’s employer, pay schedule, and immediate cash needs. Someone with reliable savings may barely use it, while someone managing irregular expenses may see its value much sooner.
My practical advice during the first week would be to treat the app as a controlled safety valve rather than free extra income. Before using earned wages early, I would look at the next regular payday and decide whether the early access solves a genuine timing problem or merely encourages spending sooner. That small pause is important because the app can improve cash flow without improving the total amount of money available.
A realistic everyday situation
Imagine working several shifts, then facing a necessary car repair before the next scheduled payday. In that situation, UKG Wallet may be more useful than a traditional budgeting app because a budget can show the shortfall but cannot provide access to wages already earned. The app’s role is narrower and more immediate: it can potentially help bridge that timing problem through the employer-supported wage process.
There is a trade-off, though. Early access can make the current problem easier while leaving less money for the later pay period. I would use it only after checking the amount needed, the effect on the next paycheck, and any transaction details shown in the app. The most responsible workflow is to use the smallest amount that solves the problem, then return to the normal pay cycle rather than turning early access into an automatic habit.
What the app is, and what it is not
UKG Wallet belongs in the business and workplace-finance space. Its store summary focuses on access to earned wages, and that focus is more useful than expecting it to behave like a conventional wallet with every possible financial feature. The name may suggest a broad digital wallet, but I would approach it primarily as an earned-pay access tool connected to employment.
That makes comparison with alternatives a little more nuanced. A bank’s overdraft facility may offer emergency liquidity, but it can involve borrowing rather than accessing pay already earned. A credit card can cover a purchase, yet it creates a balance that must be repaid. A budgeting app can help prevent future shortages, but it does not address the immediate timing of wages. UKG Wallet sits between those options: it is potentially less debt-oriented than borrowing, more immediate than planning, and more dependent on employer participation than either a bank account or a standalone budget app.
For me, that is the app’s strongest first-week advantage. It addresses a specific problem without asking the user to reorganize all personal finances. The weakness is equally specific: it cannot be judged independently from the workplace system behind it. If the connection between work records and the app feels delayed or unclear, the main benefit becomes harder to trust.
Whether it earns a place after the first month
The first month is when the novelty wears off. An app that feels helpful during one emergency still needs a sensible role in ordinary life. UKG Wallet has lasting value when it supports occasional cash-flow management without becoming the center of every pay decision. I would rather see it used deliberately a few times than opened constantly because the user has begun treating early access as part of normal spending.
Its recurring value comes from flexibility. Workers whose expenses do not line up neatly with payday may appreciate having another option when timing becomes uncomfortable. This can matter for people with variable schedules, families handling uneven weekly costs, or anyone who wants to avoid using high-cost credit for a short-lived gap. The important point is that the app’s value is situational, not universal. A person with a stable emergency fund may have little reason to use it, and that is not a failure of the app.
I would also avoid measuring success by how often the app is used. In this category, frequent use can signal a cash-flow problem rather than strong engagement. The better question is whether the app helps you handle an occasional mismatch between earned income and a due date without creating a larger problem later. That is a more realistic standard than expecting daily activity.
A useful monthly routine
After receiving pay, I would review what must remain available for rent, utilities, transport, food, and other fixed commitments before considering any early access. Then I would decide whether UKG Wallet belongs in the plan for that pay period at all. This turns the app into a deliberate checkpoint instead of an impulse button.
A second helpful habit is to keep a simple record of why early access was used. The reason might be an urgent repair, a medical-related expense, or a temporary timing issue. If the same type of expense appears repeatedly, the longer-term answer may be a sinking fund, a revised bill date, or a conversation with a financial adviser rather than repeated withdrawals through the app. UKG Wallet can help with timing, but it does not remove the need to understand the pattern behind the shortage.
One less obvious trade-off is psychological. Seeing earned wages as available before payday can make income feel more flexible than it really is. That can be helpful when used carefully, but risky when every available amount is treated as spending money. I would keep the normal payday as the anchor of the budget and regard early access as an exception. That mindset preserves the app’s usefulness without allowing it to quietly change spending behavior.
Who will get the most value
I think the app is best suited to an employee whose workplace supports it and who sometimes experiences short gaps between earning money and needing to pay for something. It may also suit someone who wants an alternative to overdraft use or credit-card borrowing for a limited cash-flow issue. The free price removes one obvious barrier to trying it, although the financial consequences of using earned wages early still deserve attention.
It is less suitable for someone seeking a complete personal-finance dashboard. If your main goal is categorizing purchases, tracking subscriptions, setting investment goals, or comparing bank accounts, you will need a different tool. It is also not the right answer for a persistent income-versus-expenses problem. In that case, a budget review, debt-support service, or professional financial guidance would address the underlying issue more directly.
Questions I would settle before relying on it
The first question is whether your employer supports the service. I would confirm that through the workplace’s normal payroll or employee-app channels rather than assuming that any employee can use it. The app is tied to employment, so eligibility is not simply a matter of downloading it.
The second question is how early access affects the next regular paycheck. I would read the amount and timing shown before confirming a transaction and avoid treating the displayed balance as disposable income. Understanding that relationship is more important than the speed of the interface.
The third question is whether the app should replace an emergency fund. My answer is no. It can be a useful bridge, but an emergency fund gives more control because it does not depend on drawing future pay forward. I would use UKG Wallet as one option within a broader plan, not as the plan itself.
The fourth question is whether it remains useful if I rarely need it. I believe it can, but only as a backup. Some apps justify their place through daily use; this one may justify its place by being available when a timing problem appears. That is a quieter kind of recurring value, and it should not be confused with a reason to check it constantly.
Maintenance, friction, and the parts that may become tiring
The maintenance burden is relatively light in concept because UKG Wallet is focused rather than overloaded with financial tools. Still, users should expect to keep their employment and account details current and pay attention to the information connected to each transaction. A wage-access app is only as useful as the accuracy and timeliness of the employment data feeding it.
That dependency is the main source of possible friction. If a shift, pay record, or eligibility status does not appear when expected, the user may not know whether the issue is in the app, the employer’s payroll process, or the timing of the work record. For someone facing an urgent bill, uncertainty can be more frustrating than a simple refusal. I would avoid waiting until the last minute to test the service for the first time.
The current version is 1.0.25, and the app supports devices running operating system version 10 or newer. Those details matter when an older phone is still in daily use. Before planning around the app, I would check the device requirement and keep the application updated through the normal app-store process. A financial tool that cannot run reliably on the only phone available is not a practical emergency option.
UKG Wallet is free and rated for Everyone, which makes trying it straightforward from an access and age-rating perspective. Free, however, should not be interpreted as consequence-free. The important cost question is how using earned wages early affects later cash flow and whether any transaction terms shown in the app fit your situation. I would read those details at the moment of use rather than relying on a general assumption about how the service works.
Where fatigue can set in
The biggest fatigue risk is repetition. If the app becomes a regular response to ordinary expenses, it may reduce the pressure to fix the monthly budget while making each future payday feel smaller. That pattern can be difficult to notice because every individual use may appear reasonable. I would set a personal rule, such as reserving the service for genuine timing problems, and review that rule if use starts becoming routine.
Another possible source of fatigue is the need to reconcile two timelines: the work already completed and the money still needed for the rest of the pay period. The app may make earned wages visible, but visibility is not the same as a complete spending plan. Users who dislike keeping track of upcoming obligations may find the convenience less liberating than expected.
There is also a trust issue that comes with any payroll-connected product. I would want to understand what amount is available, when it becomes available, and how a request changes the later payment before using the feature under pressure. If those explanations are easy to follow, the app feels like a controlled tool. If they are difficult to interpret, I would choose a slower but more familiar option, such as speaking with payroll or using an existing emergency fund.
Compared with a standard banking app, UKG Wallet may feel narrower. Compared with a credit product, it may feel less like borrowing, but it still requires discipline because future income is being brought forward. Compared with a budgeting app, it offers a more immediate response but less help with changing spending habits. Those differences explain why I would keep it alongside other financial tools rather than expecting one application to handle every money decision.
Small habits that improve the experience
Check the app before an urgent situation occurs so you understand the basic flow without making a rushed decision.
Compare any available amount with the expenses that must last until the next regular payday.
Use the smallest amount that addresses the immediate need instead of treating the full available balance as spendable.
Record repeated reasons for using early access; recurring patterns may point to a budgeting or income issue that the app cannot solve.
Keep a backup plan, such as savings or a conversation with payroll, because workplace-linked access is not the same as guaranteed emergency cash.
Those habits may sound cautious, but they suit the product’s actual role. The app is most valuable when it reduces a temporary timing problem without becoming invisible in the background of every pay cycle. The less thoughtlessly it is used, the more likely it is to remain helpful over time.
My long-term verdict on UKG Wallet
After the initial appeal fades, I see UKG Wallet as a useful specialist tool rather than a complete financial home. Its lasting space comes from solving one concrete problem: giving eligible employees a way to access earned wages when the normal payday does not match real-life expenses. That can be genuinely valuable, especially when the alternative is expensive borrowing or a missed essential payment.
I would recommend it to a friend who has confirmed workplace support, understands the effect on the next paycheck, and can use early access selectively. I would not recommend building a lifestyle around it or treating it as a substitute for savings. The strongest version of the app is a backup you control, not a feature that controls your spending rhythm.
UKG, Inc. has positioned the app in a practical corner of business finance, and its audience is substantial, with over one hundred thousand installs and around one thousand nine hundred written reviews. Those figures show that it is not merely an obscure experiment, but they do not remove the need for personal judgment. The right experience depends on employment compatibility and responsible use.
For someone who wants a daily money-management suite, I would choose a banking or budgeting alternative. For someone who occasionally needs to bridge the gap between completed work and a scheduled payday, UKG Wallet has a clearer reason to stay installed. Its recurring value is not excitement or endless features; it is the option to handle a specific cash-flow moment with more flexibility.
My final recommendation is to keep UKG Wallet as an emergency-access tool, not as an everyday spending system. Used with a normal budget, a little restraint, and a clear understanding of how earned wages affect later pay, it can earn lasting space on the phone. Used automatically whenever money feels tight, it may postpone the problem rather than solve it. That balance is the difference between a genuinely useful workplace app and a convenience that gradually becomes another financial habit to manage.
Gallery
UKG Wallet Pros and Cons
- Centralizes pay
- benefits
- and workplace information in one app.
- Useful employee self-service tools reduce the need for HR assistance.
- Supports access to schedules
- time records
- and payroll details on mobile.
- Clean layout makes common tasks relatively easy to find.
- Helpful for employees managing work-related information while away from a computer.
- Features depend heavily on the employer’s UKG configuration.
- Some actions may require repeated sign-ins or additional verification.
- Performance and available tools can vary between devices and organizations.
- Notifications may be inconsistent if permissions are restricted.
- Not useful for non-UKG employees or people without employer account access.
UKG Wallet Frequently Asked Questions
What is UKG Wallet and how does it work?
UKG Wallet is a financial wellness feature connected to eligible UKG workforce and payroll systems. It may allow employees to view available earned wages and, where supported by their employer, access part of their pay before the regular payday. The exact services depend on the employer’s UKG setup, payroll rules, location, and account eligibility, so the app should be considered an employer-linked benefit rather than a general banking application.
Who can use UKG Wallet, and how do I sign up?
UKG Wallet is generally intended for employees whose organizations have enabled the service through a compatible UKG solution. You normally need valid employer credentials, personal identification details, and a supported payment account or card, depending on the available features. If your employer has not activated UKG Wallet, downloading the app alone may not provide access. Contact your HR or payroll department if registration fails.
Can I access my wages before payday with UKG Wallet?
In supported organizations, UKG Wallet may provide access to a portion of wages that you have already earned but have not yet received. Availability is not guaranteed for every employee or pay period, and the amount can depend on hours recorded, payroll processing, employer policies, and account status. Review the displayed terms carefully, including any transfer timing, limits, or optional fees, before confirming a transaction.
Are there fees for using UKG Wallet?
The cost of using UKG Wallet depends on the feature selected and the agreement established by your employer or service provider. Some options may be free, while expedited transfers, particular delivery methods, or other optional services could involve charges. Before requesting funds, check the confirmation screen and applicable terms for the exact fee, estimated arrival time, and whether a no-cost alternative is available.
Is UKG Wallet safe to use, and what should I do if I lose access?
UKG Wallet is designed to handle employee and payment information using account-security measures, but users should still protect their login details, enable available security options, and avoid signing in through suspicious links. Do not share verification codes with anyone. If your phone is lost, credentials are compromised, or a transaction looks incorrect, contact your employer’s support team and UKG Wallet assistance promptly.














